Suite 504 · Compliance blocks
The compliance details, in one place
Mortgage website compliance comes down to details that must appear consistently on every page: NMLS IDs, state license lines, the Equal Housing statement and the right disclosures when ads get specific. The suite keeps them in central blocks every page inherits.
- 1 LO NMLS ID linked to NMLS Consumer Access
- 2 State license lines from one record
- 3 Locked footer: company NMLS, EHO statement, licensing link
Fictional example; placeholder numbers
Answer first
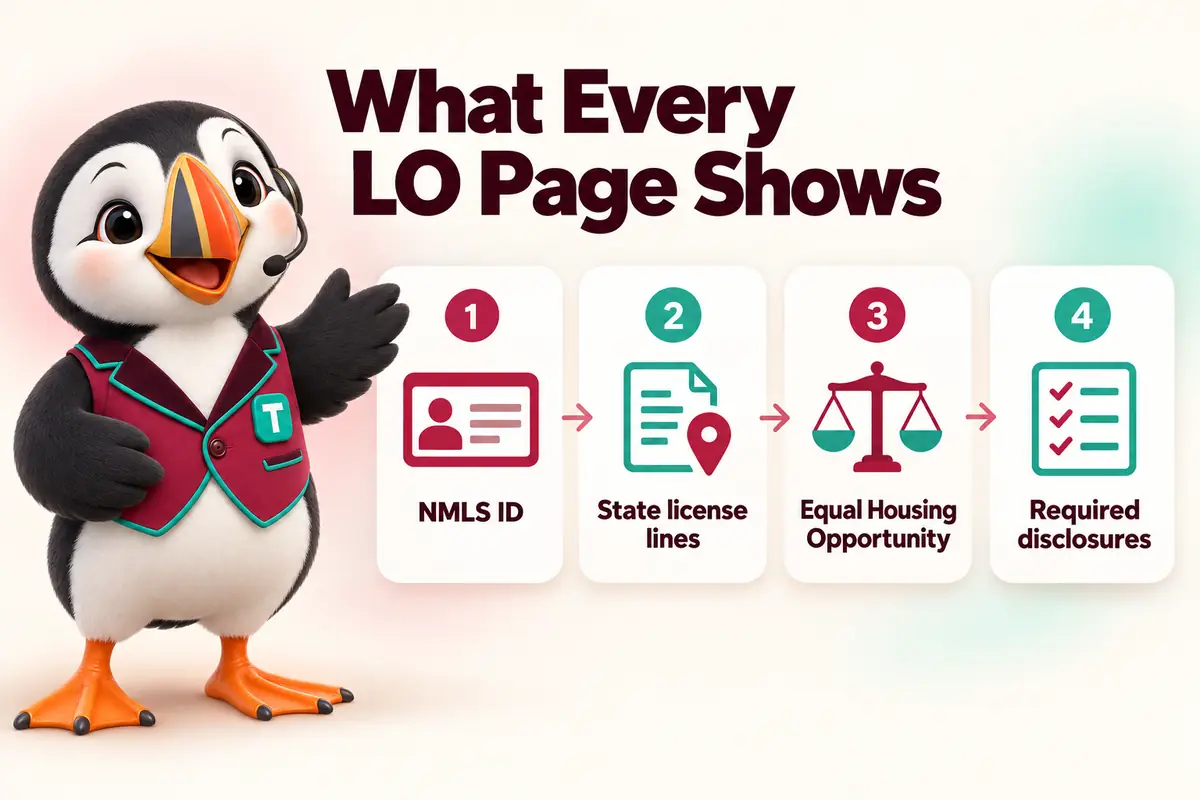
Four things every LO page carries
These four items appear on every loan officer page we build. Your compliance contact may add state-specific lines; the block system handles those too.
Regulation Z
Trigger terms and what they require
Source: CFPB Regulation Z, 12 CFR 1026.24 (advertising). Summarized for marketers; read the rule itself and ask your counsel.
| If an ad states… | Example | It generally must also state |
|---|---|---|
| The down payment amount or percentage | "Only 3% down" | Down payment, terms of repayment and the APR |
| The number of payments or repayment period | "30-year loan" | Down payment, terms of repayment and the APR |
| The amount of any payment | "$1,950 a month" | Down payment, terms of repayment and the APR |
| The amount of any finance charge | "Low closing costs of $X" | Down payment, terms of repayment and the APR |
| A rate | "6.5% rate" | The APR (and other terms as required) |
| General terms | "Flexible payment options" | Usually no trigger |
Ask the front desk
Compliance questions, answered plainly
-
YouWhat must a mortgage loan officer website show?
Funnel Suite teamCommonly: the loan officer’s NMLS ID (and the company’s), state license information where required, an equal housing statement or logo, and any disclosures required by the content (for example Regulation Z disclosures when trigger terms appear). Exact requirements vary by state and regulator, so your compliance contact confirms the list. This is general information, not legal advice.
-
YouWhat is the NMLS ID and where should it appear?
Funnel Suite teamThe Nationwide Multistate Licensing System assigns unique identifiers to companies and individual loan originators. Many rules require it on advertising and websites; we place it on each LO page and in the footer, linked to NMLS Consumer Access.
-
YouWhat are Regulation Z trigger terms?
Funnel Suite teamUnder Regulation Z’s advertising rules (CFPB Regulation Z, 12 CFR 1026.24 (advertising)), certain specific terms in an ad, such as the down payment amount, number of payments or repayment period, the payment amount, or the finance charge, "trigger" extra disclosures like the APR and terms of repayment. Our templates avoid trigger terms by default and route content that uses them to approval.
-
YouDo we need the Equal Housing Opportunity logo?
Funnel Suite teamFair housing advertising guidance (HUD Fair Housing advertising guidance (24 CFR Part 109)) encourages the logo or statement in housing-related advertising, and many lenders are required to display it. We display the official text statement by default; if you supply the official logo asset, we use it unaltered.
-
YouCan an LO put rates on their page?
Funnel Suite teamOnly through your approval workflow with the required disclosures attached and a process for keeping them current. Stale rate claims are a common finding in exams.
-
YouDo you provide compliance review?
Funnel Suite teamNo. We provide tools (blocks, approvals, logs) and flag common risks. Your licensed staff and counsel decide what is compliant.
-
YouHow do disclosure blocks stay current?
Funnel Suite teamThey are edited once, by the owner or compliance role, and every page that uses the block updates. Version history shows what changed and when.
-
YouWhat about accessibility?
Funnel Suite teamOur pages target WCAG 2.2 AA: keyboard operation, contrast, labels and focus states. See our accessibility statement.
-
YouWhat about texting and calling rules?
Funnel Suite teamConsent capture, opt-out handling and carrier registration are built in. See SMS and our TCPA and 10DLC guide.
No question matches that. Search the help center or ask us directly.
Walk your compliance officer through the blocks
We’ll show where every disclosure lives, how approvals work and what the audit export contains.
Free 30-minute walkthrough · no obligation · reply within 1 business day